


Special tax on non-reusable plastic packaging
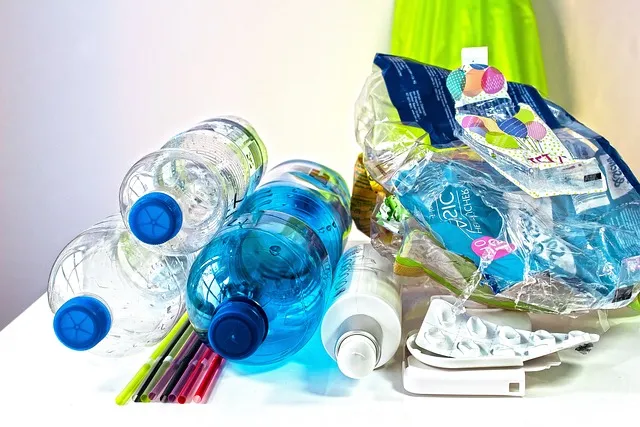
On April 9, 2022, Law 7/2022, on Waste and Contaminated Soils for a Circular Economy, was approved. This law incorporates the plastic packaging tax proposed by the European Union (EU) under the “Green Deal,” which allows financial penalties to be implemented with the aim of increasing the amount of plastics recycled at the end of their useful life.
On January 1, 2023, a special tax on non-reusable plastic packaging will enter into force. Its purpose is to encourage the prevention of the generation of waste from non-reusable packaging and to promote the recycling of plastic waste, thereby contributing to the circular economy of this material.
Under the legislation, any product intended to perform the function of containing, protecting, handling, distributing, and presenting goods will be considered packaging. Consequently, this tax will directly affect:
• Non-reusable packaging (bags, shrink film, trays, boxes, etc.)
• Semi-finished plastic products intended for obtaining plastic, and products containing plastic intended for closure
• The marketing or presentation of non-reusable packaging
The following are NOT PACKAGING: articles that form an integral part of a product throughout its entire useful life and all elements intended to be used, consumed, or disposed of (for example: boxes containing coffee capsules).
Who the Special Tax on Non-Reusable Plastic Packaging applies to
The tax on non-reusable plastic packaging is a tax whose taxable event consists of:
• Manufacture
• Importation
• Intra-Community acquisition
• Irregular introduction
The Special Tax on Non-Reusable Plastic Packaging applies to the following plastic packaging:
1. Non-reusable packaging containing plastic.
2. Semi-finished plastic products intended for obtaining packaging, such as preforms or thermoplastic sheets.
3. Products containing plastic intended to enable the closure, marketing, or presentation of non-reusable packaging.
Paints, inks, lacquers, and adhesives designed to be incorporated into products intended to perform the function of containing, protecting, handling, or delivering goods or products will not be subject to the Special Tax on Non-Reusable Plastic Packaging.
Nor will small imports or intra-Community acquisitions of packaging (those in which the total quantity of non-recycled plastic contained in the packaging does not exceed 5 kilograms) be taxed under the Special Tax on Non-Reusable Plastic Packaging.
Likewise, products intended to perform the function of containing, protecting, handling, distributing, and presenting medicinal products, medical devices, food for special medical purposes, infant formula for hospital use, or hazardous healthcare waste, as well as plastic rolls for silage used in agriculture and livestock farming, are exempt from the plastic packaging tax.
Tax base
The tax base will consist of the quantity of non-recycled plastic, expressed in kilograms, contained in the products, and the tax rate will be €0.45 per kg.
The tax base of the Special Tax on Non-Reusable Plastic Packaging will consist exclusively of the quantity of non-recycled plastic, expressed in kilograms, incorporated into those products.
The quantity of recycled plastic contained in the products must be certified by an entity accredited to issue certification under standard UNE-EN 15343:2008 “Plastics. Recycled plastics. Traceability and assessment of conformity of plastics recycling and recycled content”
Accrual
• Manufacture
In the case of manufacture: at the time of the FIRST DELIVERY or of the products being made available to the acquirer. The invoice must state:
– The kg of non-recycled plastic.
– Whether any exemption applies.
– The tax payable.
• Intra-Community acquisition
In intra-Community acquisitions, the tax accrues on the 15th day of the month following the month in which the dispatch or transport of the products begins, except where an invoice is issued before that date, in which case accrual will take place on the date the invoice is issued.
• Imports
In imports: at the time import duties accrue under customs legislation
• Irregular introductions into the market
In the case of irregular introductions into the market, if the time at which the products were introduced is not known, the irregular introduction will be deemed to have occurred in the earliest tax period that is not time-barred.
Infringements and penalties
• Failure to register in the census: €1,000.
• Incorrect declaration of the kg of plastic: penalty of 50% of the unpaid tax, with a minimum of €1,000. The penalty will be increased by 25% in the event of repeat offenses.
• Incorrect application of exemptions: penalty of 150% of the tax benefit improperly applied, with a minimum amount of €1,000.
• Incorrect data on the sales invoice: penalty of €75 per incorrect invoice or certificate issued.
How the special tax will be administered
The Ministry of Finance will establish the forms, deadlines, and conditions for filing self-assessment returns for the Special Tax on Non-Reusable Plastic Packaging.
Taxpayers subject to the tax will be required to register, before commencing their activity, in the Territorial Register of the Special Tax on Non-Reusable Plastic Packaging.
In addition, manufacturers designated by Ministerial Order will be required to keep accounting records of the products falling within the objective scope of the tax.
Keep reading

Shareholder exit through a capital reduction: two routes to channel liquidity and their taxation
A capital reduction can be used to channel liquidity from a company to one or more shareholders without having to distribute a dividend to all…

Spanish tax authorities reassess retirement pensions and pension plan withdrawals of Spaniards under Portugal’s Non-Habitual Resident regime
The tax audit bodies of the Spanish Tax Agency (AEAT) are reassessing Spanish pensioners who, after moving to Portugal under the Non-Habitual Resident regime (NHR),…

The Spanish Tax Agency reverses a change in position applied de facto: U.S. entities may recover input VAT incurred in Spain by submitting an IRS certificate and a Resale Certificate
Supplementary report of the National Tax Management Office (Oficina Nacional de Gestión Tributaria) of April 28, 2026 (available here). Starting in mid-2025, businesses and professionals…
Explore the blog
Categories
Recent posts

Royal Decree-Laws 28/2026 and 29/2026 and the new regime for residential leases (II): tax measures
Royal Decree-Laws 28/2026 and 29/2026 and the new residential lease regime (I): lease term, evictions, and transfers

Setting up a holding company mid-year: how is the main remuneration requirement for the Wealth Tax exemption calculated?

Holding company management services to subsidiaries are not a single supply for VAT purposes: implications of the Högkullen judgment for Spanish groups

The Supreme Court relaxes the employee requirement for rental companies in family groups: a step forward, with caveats
