


ROYAL DECREE - MUNICIPAL CAPITAL GAINS TAX (PLUSVALÍA MUNICIPAL)

| Yesterday, November 9, 2021, the Official State Gazette (BOE) published Royal Decree-Law 26/2021PDF, of November 8, approved yesterday by the Council of Ministers, which adapts the consolidated text of the Law Regulating Local Government Finance, approved by Royal Legislative Decree 2/2004, of March 5, to the recent case law of the Constitutional Court (TC) on the Municipal Capital Gains Tax (IIVTNU, 'plusvalía municipal'). According to the preamble (exposición de motivos) of the legislation, this royal decree-law seeks to respond to the Court’s mandate, even though its latest judgment, dated October 26, 2021, has not yet been published in the BOE, to make the relevant amendments or adaptations to the legal regime of the tax as a result of the most recent of the judgments handed down by the TC, and to incorporate the case law contained in earlier judgments, in order to give unity to the rules governing the tax and to comply with the ability-to-pay principle (principio de capacidad económica). Although we will provide a more detailed analysis in the coming days, we set out below the most notable aspects of this legislative adaptation: Nature of the tax: It remains unchanged: the tax is levied on the increase in the value of land that becomes apparent at the time the tax accrues and has arisen over a period of 20 years. New non-taxation scenario (supuesto de no sujeción): A new non-taxation scenario is introduced for cases in which it is established, at the request of the interested party, that no increase in value has occurred. The interested party must report the transfer and provide the deeds documenting the transfer and the acquisition. To establish the absence of an increase in value, the transfer or acquisition value taken will be the higher of the value stated in the deed documenting the transaction and the value verified, where applicable, by the tax authorities, under the new power granted to city councils. Determination of the tax base: The tax base will be the result of multiplying the cadastral value of the land at the time of accrual by the coefficients approved by the city councils, which may in no case exceed the following (depending on the number of years since acquisition): 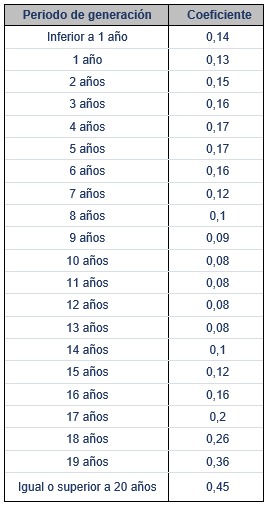 |
| The coefficients will be updated annually by a provision with the rank of law (this may be done, for example, in the General State Budget Law, LPGE). Solely for the purposes of this tax, city councils may apply a downward correction of up to 15% to the cadastral values of land, depending on how up to date those values are. This objective calculation system becomes optional, since taxpayers may choose to be taxed on the basis of the actual capital gain obtained at the time of the transfer of a property, which is determined as the difference between the transfer value and the acquisition value of the land, provided they prove that this gain is lower. For these purposes, in transfers of a property comprising both land and a building, the actual capital gain on the land will be equal to the difference between the sale price and the acquisition price after applying to it the proportion that the cadastral value of the land represents of the total cadastral value. These calculations may be verified by the city councils. Capital gains generated in less than one year: As a new development, capital gains generated in less than one year will be taxed. Adaptation of municipal tax ordinances City councils will have six months from the entry into force of the Royal Decree-Law to bring their rules into line with the new legal framework. In the meantime, the provisions of the royal decree-law will apply, and the maximum coefficients established in it will be used to determine the tax base. Entry into force: The Royal Decree-Law will enter into force on the day following its publication in the BOE, that is, on November 10, 2021. |
Cited documents
Rulings, decisions, judgments and legislation cited in this article, available to download as PDF (in Spanish unless otherwise stated).
- Download PDF287 KB
Legislation (BOE)
Real Decreto-ley 26/2021, de 8 de noviembre, por el que se adapta el texto refundido de la Ley Reguladora de las Haciendas Locales, aprobado por el Real Decreto Legislativo 2/2004, de 5 de marzo, a la reciente jurisprudencia del Tribunal Constitucional respecto del Impuesto sobre el Incremento de Valor de los Terrenos de Naturaleza Urbana.
Official source: Agencia Estatal Boletín Oficial del Estado (boe.es)
Public-sector documents reused with attribution of their source (Spanish Law 37/2007 on the re-use of public sector information and Commission Decision 2011/833/EU). DGT rulings and TEAC decisions have been laid out as PDF from their official text; BOE legislation and Court of Justice judgments are the PDF published by the issuing body. Spanish court judgments are the anonymised document published by the General Council of the Judiciary; source: Centro de Documentación Judicial (CENDOJ) del CGPJ, with its ECLI identifier. The authentic text is the one at the linked official source. Source of the legislation data: Agencia Estatal Boletín Oficial del Estado.
Keep reading

The Supreme Court relaxes the employee requirement for rental companies in family groups: a step forward, with caveats
Supreme Court judgments (STS) 637/2026 of February 17 (appeal no. 1196/2024), 640/2026 of February 19 (appeal no. 1326/2024), and 874/2026 of February 20. _____________________________________________ One…

Regularization of FEAC transactions lacking valid economic reasons: the temporal and material scope of the adjustments according to the TEAC
The special tax regime applicable to certain business restructuring transactions (the special tax-neutrality regime for mergers, divisions, contributions of assets and exchanges of shares, or…

Holding company management services to subsidiaries are not a single supply for VAT purposes: implications of the Högkullen judgment for Spanish groups
Judgment of the Court of Justice of the European Union (CJEU) of July 3, 2025 (Case C-808/23, Högkullen AB) The relationship between holding companies and…
Explore the blog
Categories
Recent posts

Royal Decree-Laws 28/2026 and 29/2026 and the new regime for residential leases (II): tax measures
Royal Decree-Laws 28/2026 and 29/2026 and the new residential lease regime (I): lease term, evictions, and transfers

Shareholder exit through a capital reduction: two routes to channel liquidity and their taxation

Spanish tax authorities reassess retirement pensions and pension plan withdrawals of Spaniards under Portugal’s Non-Habitual Resident regime

The Spanish Tax Agency reverses a change in position applied de facto: U.S. entities may recover input VAT incurred in Spain by submitting an IRS certificate and a Resale Certificate
